
Algorithmic Groupthink and the Consensus Trap: Predictive Modelling Deficits in the $12 Trillion Asset Base
Interest Rates (21210) +1.0049σ Q1 2026
Banking & Lending Regulation (21350) −1.4085σ Q4 2025
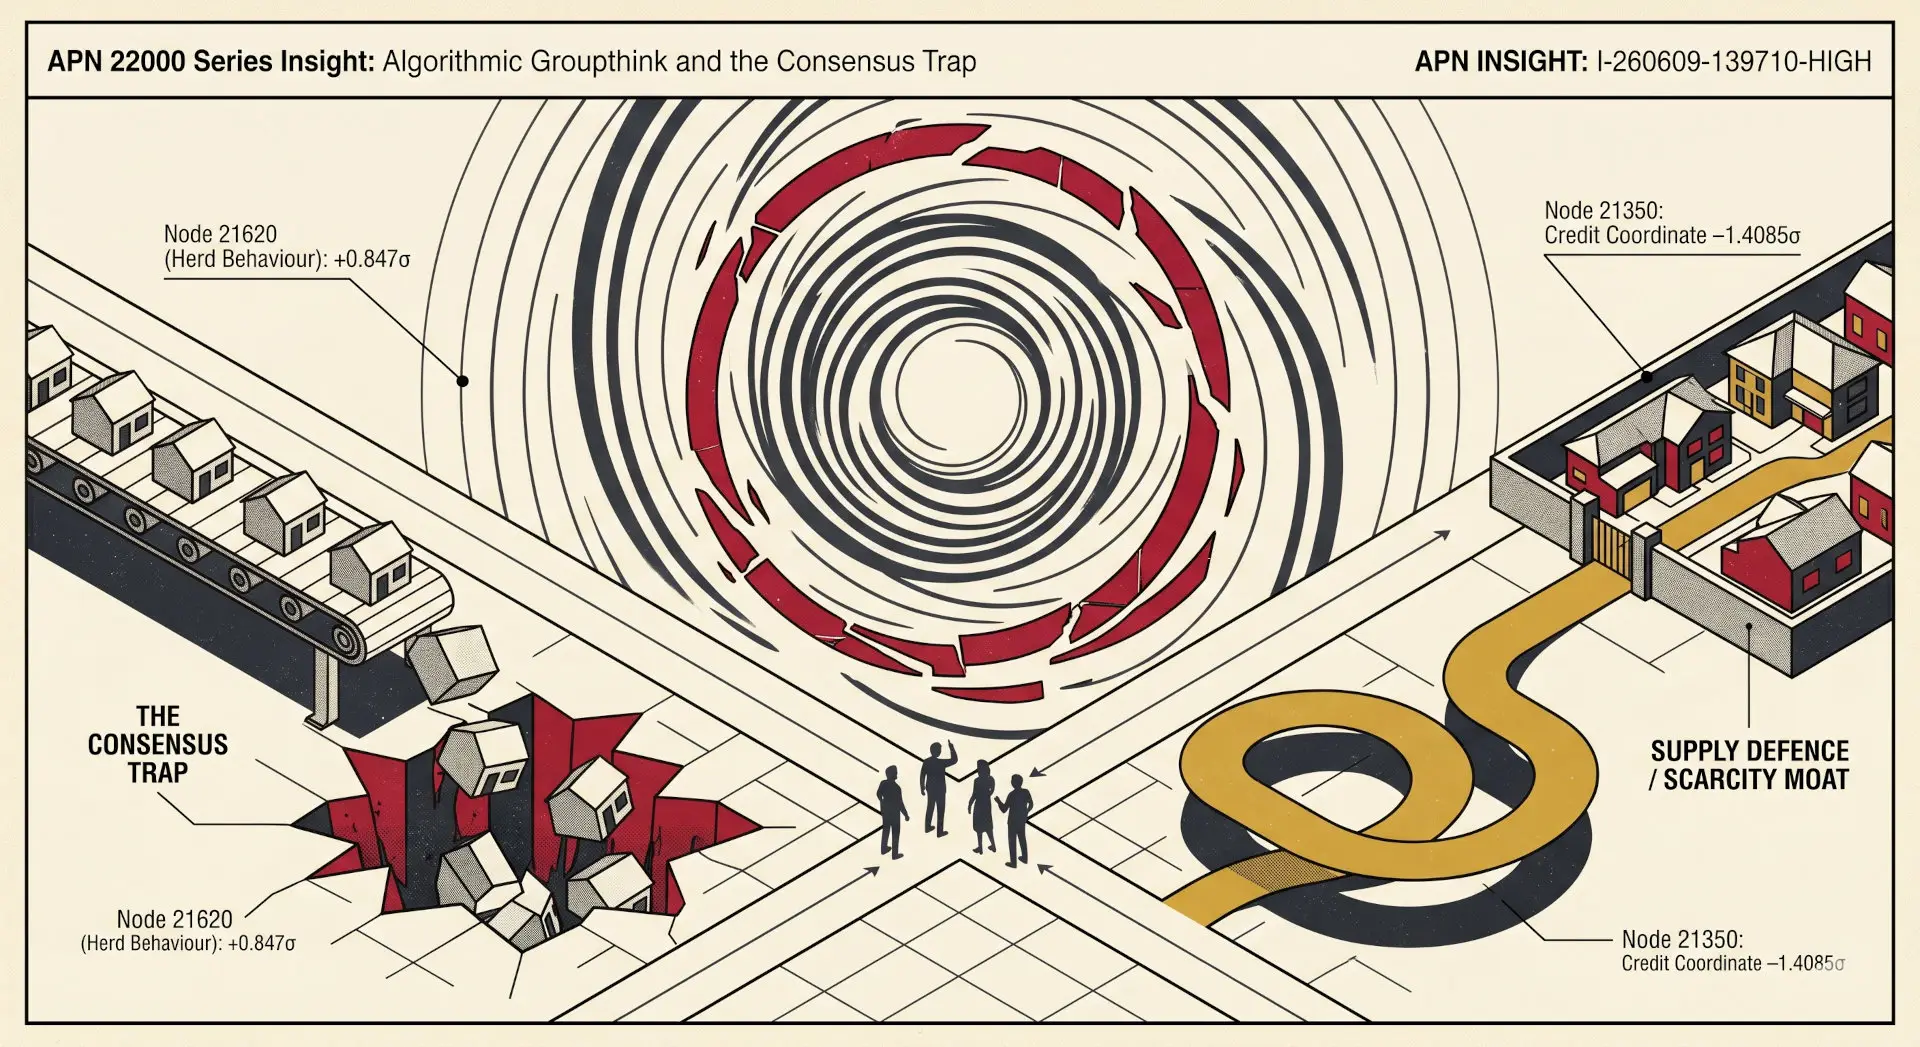
Market Psychology & Herd Behaviour (21620) +0.7018σ Q4 2025
Scope and Purpose
The increasing reliance of market intermediaries and buyers’ agents on commercial PropTech applications and general large language models (LLMs) introduces a documented structural dislocation across the Australian residential asset base, valued in excess of $12 trillion. This output sets out the research findings presented on The Elephant In The Room Property Podcast by Microburbs founder Luke Metcalfe, in conversation with co-hosts Veronica Morgan and Chris Bates, and reads them against the certified rate, regulatory and behavioural settings the Australian Property Network (APN) tracks.
The Consensus Echo Chamber: Systemic Limitations of Generative Modelling
Metcalfe’s central finding is that the mathematical architecture of generic generative tools, which optimises for sequential linguistic probability rather than multi-dimensional economic causality, leaves them structurally unable to navigate cyclical turning points or macroprudential interventions. In a baseline audit testing seven discrete generative models across 17,000 historical suburb profiles over a 38-month window, six of the seven systematically underperformed a simple randomised selection. On his figures, that predictive deficit carried an average asset misallocation cost of about $13,000 per transaction relative to baseline market momentum.
The mechanism is training data. Because LLMs learn from historical text dominated by real estate promotional copy and uniform spatial narratives, their outputs are an automated consolidation of legacy consensus views rather than forward-looking analysis. Reliance on uncalibrated consumer-facing automation strips cyclical nuance from spatial risk assessment, converting localised data points into consensus noise.
Algorithmic Narrative Amplification and Spatial Purchasing Funnels
Market Psychology & Herd Behaviour (21620) reads +0.7018σ for the December 2025 quarter, an elevated behavioural-momentum setting before any allowance for algorithmic amplification. When multiple buyer agencies deploy identical prompts to isolate the same growth corridors, the structural implication is a synthetic compression of the spatial purchasing funnel: uncorrelated capital is channelled into identical local government areas independent of infrastructure capacity or local credit conditions. If current trajectories persist, participants relying on unverified generic tools are likely to pay an unbacked premium to enter congested, consensus-driven market pockets, creating the conditions for localised capital contraction when macroeconomic settings shift.
The hosts’ own historical review widens the point beyond software. Macro-level forecasts published by traditional media commentators return, on their count, an 85% failure rate over a ten-year horizon, matching the underperformance observed in generic digital tooling. Both human and algorithmic forecasters lean heavily on suburb median prices, a metric in which 30% to 40% of observed positive variance is driven by structural additions and renovations rather than land value accretion. When a cohort moves from entry-level dwellings to heavily improved assets, the median registers an artificial escalation that masks stagnant underlying land values. Sophisticated risk evaluation therefore requires a move away from median indicators toward property-specific resale tracking that isolates improvement expenditure from location value.
Micro-Market Segmentation and Cohesion
A foundational error of automated forecasting is treating the residential landscape as a monolith. Metcalfe’s cohesion metrics, measuring the share of properties moving in the same direction over a given period, show clear drop-offs by scale:
- National: about two-thirds (66%) of observed properties move in the same direction.
- Suburb: cohesion rises to about 90%, leaving a persistent one-in-ten deviation where individual assets buck the local trend because of asset-class mismatches, such as a three-bedroom post-war house against a five-bedroom premium dwelling.
- Street: cohesion reaches about 97%, establishing that true sub-markets operate at the street and immediate-pocket level rather than the suburb grid.
The Paradox of Convenience: Infrastructure Signals and Supply Defence
The research also identifies a negative correlation between superficial liveability metrics and long-term capital growth, a blind spot in standard consumer algorithms. Automated models routinely flag commercial infrastructure, such as new rail lines, bus networks and high-density retail, as positive growth indicators. Micro-historical tracking shows those convenience markers are better read as predictors of state government density rezoning: the high-density construction that follows creates supply shocks that, on Metcalfe’s data, depress value performance up to a 7-kilometre radius.
Conversely, a tranquillity measure maps a strong positive correlation with superior capital growth, driven by a community’s capacity for supply defence. Close-knit, high-socioeconomic communities have the social capital to resist development and zoning change, preserving structural scarcity. Counter-intuitive micro-signals reinforce the same scarcity model, including a correlation between fast-food outlets within a 2-kilometre radius and long-term capital underperformance relative to the regional baseline.
The Transience of Speculative Capital and Post-Budget Friction
Transaction life-cycle data challenges the conventional narrative of the long-term buy-and-hold investor. The median holding period for an investor is 5.5 years against 6.5 years for an owner-occupier, and the most recent investor purchaser on a given street shows the highest probability of subsequent sale, driven by life shocks, divorce or cash-flow stress.
That transience is amplified by the May 2026 Federal Budget’s changes to investor incentives, including the compression of negative gearing, tighter land tax settings and altered capital gains tax treatment, against a rate and regulatory backdrop that is itself restrictive. Interest Rates (21210) reads +1.0049σ for the March 2026 quarter with the cash rate at 4.35%, and Banking & Lending Regulation (21350) reads −1.4085σ for the December 2025 quarter on APRA’s sustained 3.00 percentage point serviceability buffer, a contractionary credit setting that removes the viability of low-yield, tax-optimised residential strategies such as regional momentum plays or high-density inner-city units.
The prospective trajectory is a structural migration of capital away from speculative retail property investment toward corporate structures, specialised commercial operators such as institutional short-stay accommodation, or direct equity in the primary family home. Because roughly two-thirds of the Australian housing stock is owner-occupied, long-term capital stability remains insulated within premium owner-occupier pockets, where emotionally committed, well-capitalised buyers set a pricing floor independent of investor cash-flow metrics.
APN Analytical Synthesis
The balance of evidence is structurally consistent with a market in which behavioural momentum is already elevated and generic algorithmic tooling amplifies it, funnelling capital into consensus locations at exactly the point in the cycle when the rate and regulatory settings are least forgiving of an unbacked entry premium. The research findings recorded here are the podcast’s own and are not independently verified by APN; what the certified readings add is the setting in which they land: elevated herd behaviour, an elevated cost of finance and a contractionary credit rule. This synthesis speaks only to the structural conditions the cited data can support; it does not constitute a view on future prices, and no such view is expressed or implied.
Source
- Primary source: The Elephant In The Room Property Podcast, episode “Luke Metcalfe: Why AI Can’t Pick Property Winners”.
- Hosts: Veronica Morgan (buyers’ agent and mentor) and Chris Bates (mortgage broker).
- Subject matter expert: Luke Metcalfe, founder of Microburbs.
- Episode URL: https://youtu.be/h2MEhzrXHbE?si=mxh927Ic1WLXu2NG
- Retrieval date: 9 June 2026. Paraphrase throughout; the episode is the authoritative record of exact wording.
Disclaimer
The analysis, information, and opinions contained in this article are for general informational and strategic purposes only and do not constitute financial, investment, legal, or any other form of professional advice. The Australian Property Network (APN) is a strategic intelligence organisation and is not a licensed financial advisor.
The views, thoughts, and opinions expressed in this text belong solely to the author and do not necessarily reflect the official policy or position of the Australian Property Network (APN).
This content may be based on data from third-party sources believed to be reliable; however, APN provides no warranty as to its accuracy, currency, or completeness. Images used are for illustrative and conceptual purposes only and may not represent real persons, properties, or events.
Note, September 2026: Banking & Lending Regulation (21350) now records APRA’s lending rules as a register and no longer publishes a standardised reading. The −1.4085σ above was its certified reading at the date of publication.
Property values and market conditions can go down as well as up. Before making any property or investment decisions, you must conduct your own thorough research and seek independent professional advice tailored to your specific circumstances.
Last updated: 5 September 2026.