Of the home loans that banks and other deposit-taking lenders funded in the June quarter 2026, 36.5% by value went to investors, up from 29.5% in March 2019. The ABS, counting new loan commitments without refinancing, puts investors’ share at 38.7%. The two measures disagree about the level, because one includes refinanced loans and the other leaves them out, but they agree about the direction: both reached their highest in the September quarter 2025. APRA’s collection begins in March 2019, so for APRA that means the highest since then; on the ABS measure it was the highest since June 2015. Investors’ share had been rising since 2021 on the ABS measure and since 2023 on APRA’s.
Banking & Lending Regulation (21350) sets out lending rules as a register and publishes no standardised reading.
Two ways of counting new lending
Two official sources report new home lending split by purpose. The Australian Prudential Regulation Authority (APRA) collects, from the banks, credit unions and building societies it supervises, the value of new home loans funded each quarter, split between owner-occupied and investment loans. The Australian Bureau of Statistics (ABS) publishes new loan commitments, the loans lenders have approved and borrowers have accepted, split between owner occupiers and investors, and it leaves refinancing out.
| APRA quarterly property exposures | ABS Lending Indicators | |
|---|---|---|
| What is counted | Loans funded (money paid out) in the quarter | Loans committed (approved and accepted) in the quarter |
| Refinancing | Included, including loans moved from another lender | Excluded |
| Lenders | Banks, credit unions and building societies, other than those APRA classes as other ADIs | All lenders, including non-bank lenders |
| Purpose split | Owner-occupied and investment term loans | Owner occupier and investor |
| June quarter 2026, owner-occupier | $123.6 billion | $60.7 billion |
| June quarter 2026, investment | $71.1 billion | $38.3 billion |
Sources: APRA, Quarterly ADI Property Exposures, June 2026 (released 17 September 2026), Table 1c; ABS, Lending Indicators, new loan commitments for total dwellings excluding refinancing, original series.
The APRA figures are roughly twice the ABS figures, and most of the difference is refinancing. A borrower who moves an existing loan to a new lender appears in APRA’s new loans funded, because the new lender pays out a new loan, but not in the ABS figures, because no new borrowing has taken place.
New lending by purpose, APRA
New home loans funded by purpose, by quarter
Billions of dollars, term loans, authorised deposit-taking institutions other than those APRA classes as other ADIs. Includes refinancing. Not adjusted for inflation. Source: APRA, Quarterly ADI Property Exposures, June 2026, Table 1c.
Between the June quarters of 2019 and 2026, owner-occupied loans funded rose from $58.6 billion to $123.6 billion a quarter, and investment loans from $25.9 billion to $71.1 billion. Investment lending grew faster: it is 2.7 times its June 2019 level, against 2.1 times for owner-occupied lending. These are current dollars, and some of the growth reflects higher dwelling prices and larger loans rather than more borrowers.
Investors’ share on each measure
Investors’ share of new home lending by value, APRA and ABS
Per cent. APRA: investment term loans as a share of owner-occupied and investment term loans funded, including refinancing. ABS: investor commitments as a share of owner occupier and investor commitments, excluding refinancing, from the September quarter 2019. Sources: APRA, Quarterly ADI Property Exposures, June 2026; ABS, Lending Indicators.
On APRA’s measure, investors’ share of new lending held between about 28% and 31% from 2019 to 2022, then rose to 37.4% in the September quarter 2025 and stood at 36.5% in June 2026. The ABS measure moves further. It fell to 23.5% in December 2020, when owner-occupier commitments rose faster than investor commitments, then climbed to 40.7% in September 2025. Up to June 2021 the ABS share was the lower of the two; from September 2021 it has been higher in every quarter.
Refinancing is one reason the two differ. It adds a large amount to APRA’s figures in every quarter and none to the ABS figures. APRA does not split refinancing by purpose, so how much of the gap between the two shares it explains cannot be measured from the published data. The two also differ in timing, since a loan is committed before it is funded, and in coverage, since the ABS includes non-bank lenders.
Refinancing in the APRA figures
External refinancing as a share of new loans funded, by quarter
Per cent of the value of all new loans funded, authorised deposit-taking institutions other than those APRA classes as other ADIs. Gold marks the latest quarter. APRA does not split refinancing by purpose. Source: APRA, Quarterly ADI Property Exposures, June 2026, Table 1c.
Loans refinanced from another lender have made up between 33% and 48% of APRA’s new loans funded in every quarter since 2019. The share was above 42% in each quarter from September 2022 to September 2023, during the interest rate rises of those years, and peaked at 47.8% in March 2023. It was 37.3% in June 2026. APRA does not split refinancing by purpose, so its figures cannot be restated on the ABS basis.
What this does not show
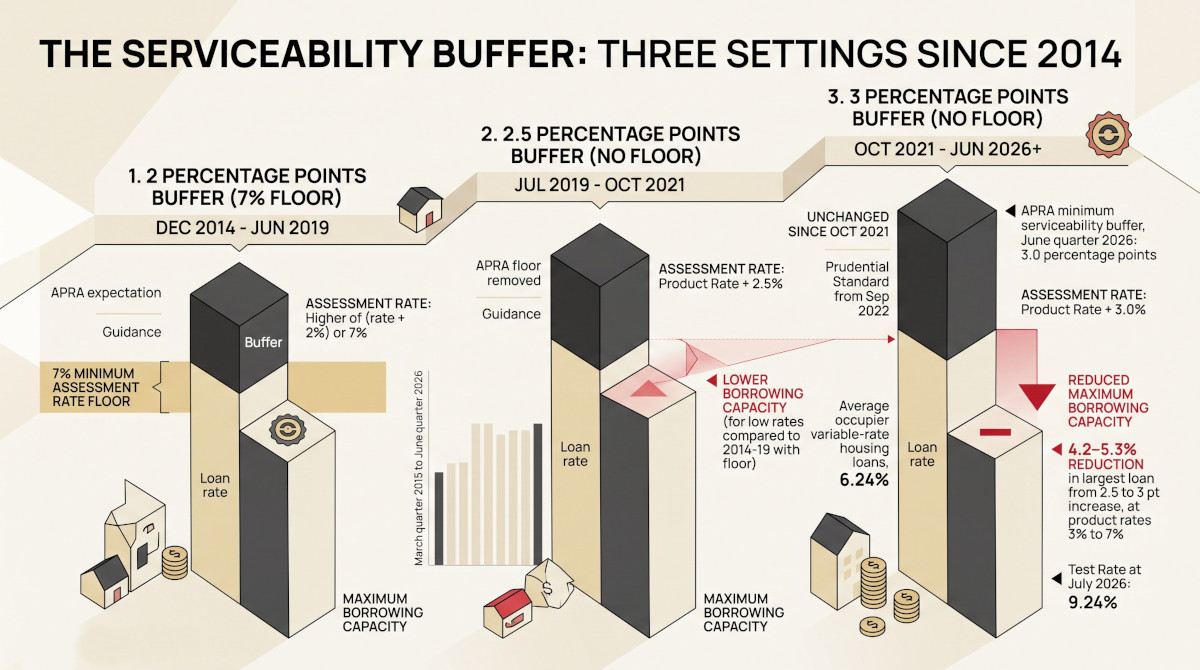
Neither source says why investors’ share has risen, and a share can rise because investor borrowing grows faster or because owner-occupier borrowing grows more slowly. Both are shares of value, so larger average investment loans lift the share without more investors. The APRA figures exclude non-bank lenders, which the ABS includes. How much of new lending is at high debt-to-income ratios is covered in High Debt-to-Income Lending Since 2019, the serviceability buffer lenders apply in The Serviceability Buffer: Three Settings Since 2014, and first home buyers against investors in First Home Buyers and Investors: Fifteen Years of the Lending Growth Race.
Findings are presented on the basis of data and evidence alone.