
Scope 3 Reporting and the 1.15% ‘Brown Penalty’ in Agribusiness Lending
None declared. The indices this event bears on — APN Climate-Risk Asset Devaluation Index™ (24500), APN Regional Brown Discount™ (24520), APN Bedrock™ (24110) and APN Sovereign Policy Composite Index™ (24800) — carry no certified reading derived from it.
Executive Summary
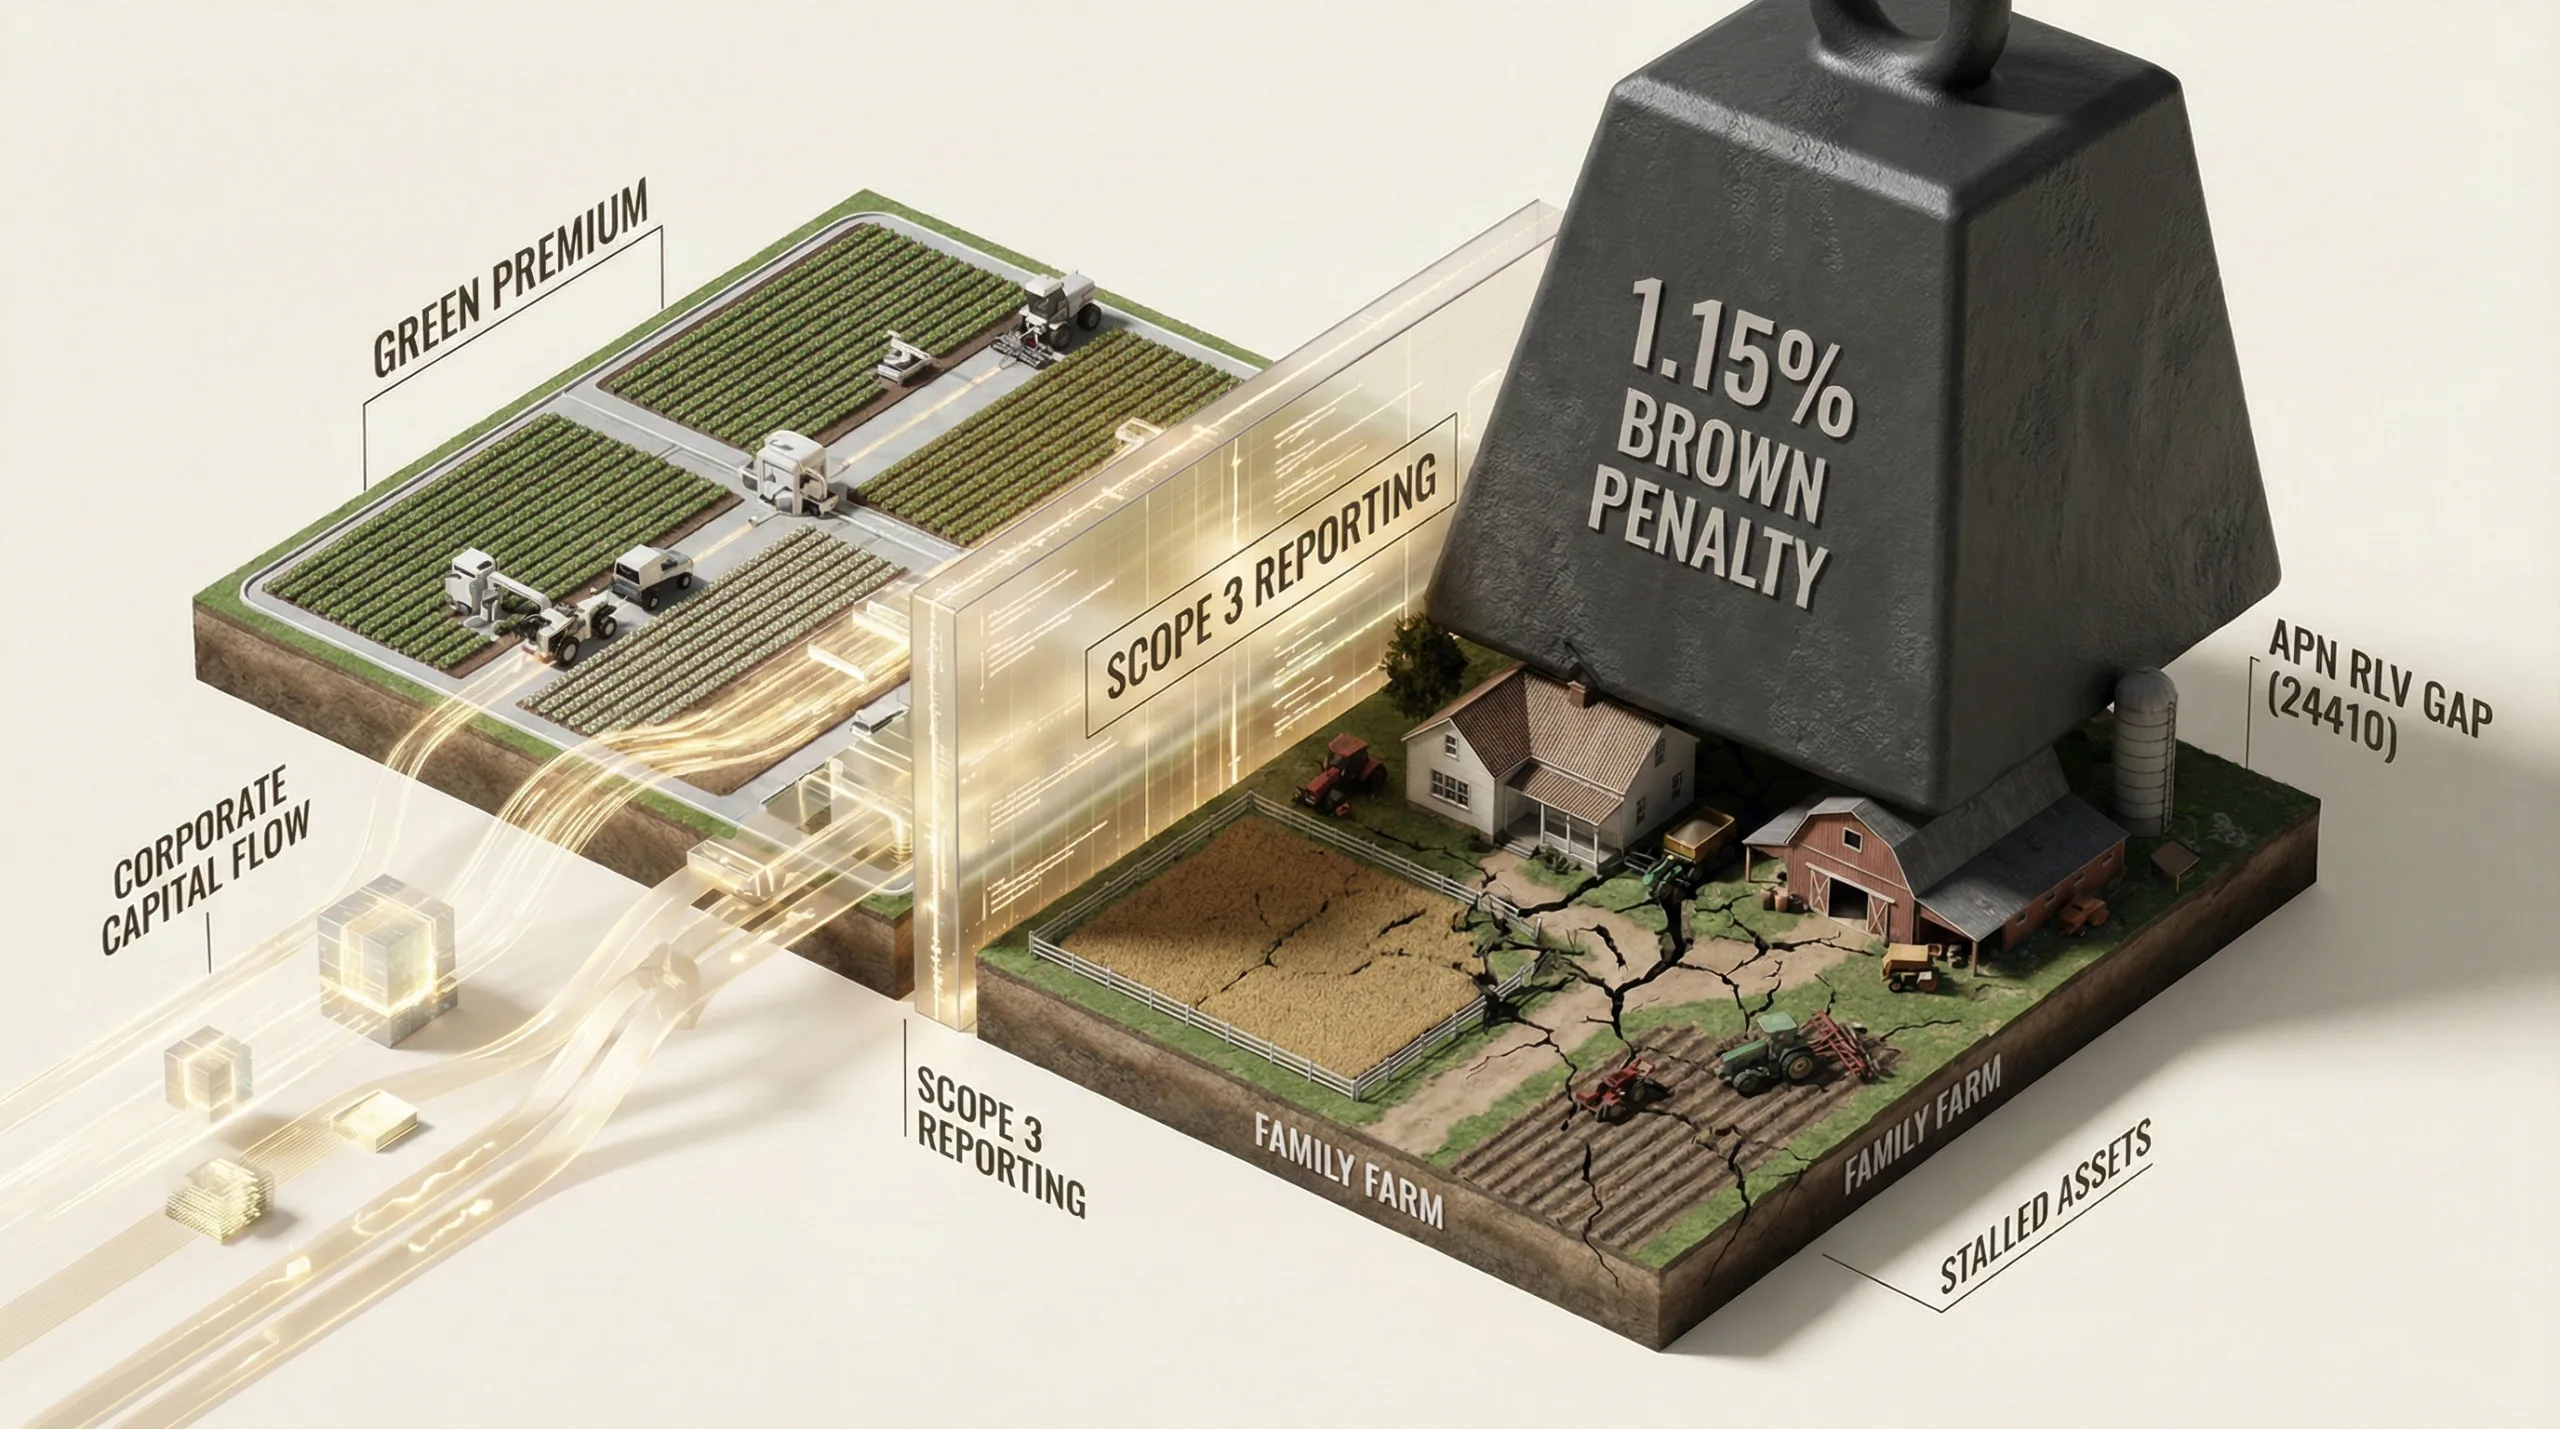
Mandatory Scope 3 emissions reporting has created a bifurcated credit market in Australian agribusiness that structurally disadvantages family farms. The core mechanism is a ‘Sustainability Risk Premium’—in practice a ‘Brown Penalty’—imposing a cost-of-capital differential of between 0.65% and 1.15% on operators unable to meet the data-intensive compliance demands of their lenders. This is not an anomalous market outcome; it is a direct consequence of Tier 1 banks transferring their own regulatory obligation to report ‘financed emissions’ to their borrowers.
For property professionals, this is a recalibration of asset valuation in the rural sector. The emergence of a ‘Brown Discount’ on data-poor land and a corresponding ‘Green Premium’ on compliant assets is creating a two-speed market defined by data-readiness. An asset’s capacity to generate audit-grade environmental data is now as material as soil quality or water rights, bearing directly on valuation method, transaction viability and client advice.
Background & Strategic Context
This event bears directly on two of APN’s standing frameworks: the ‘Wealth Funnel’ thesis and the APN Sovereign Policy Composite Index™ (SPCI, 24800). The regulatory shift, in the form of the Australian Sustainability Reporting Standards (ASRS), has created a market mechanism that channels assets from one class of owner (data-poor family farms) to another (data-rich corporate aggregators)—the Wealth Funnel in operation.
The regulatory catalyst (APN Sovereign Policy Composite Index™, 24800): The domestication of ISSB standards into Australian law is a state-level intervention that redefines ‘creditworthiness’ to include ‘climate data availability’. Banks, as regulated entities, are compelled to enforce those standards on their loan books, making them de facto regulators of the agricultural sector and initiating the asset reallocation mechanism.
The value shift (APN Climate-Risk Asset Devaluation Index™, 24500, and APN Regional Brown Discount™, 24520): The 0.65%–1.15% ‘Sustainability Risk Premium’ is the first hard market quantification of the brown-discount mechanism these indices describe. Climate transition risk is no longer a theoretical ESG concept but a direct, measurable financial penalty on asset viability and valuation.
The social capital risk (APN Bedrock™, 24110): Accelerated consolidation of family farms by corporate entities is a risk to the social cohesion APN Bedrock™ measures. A diminished presence of family-run operations weakens local institutions, reduces resident stability and affects the social fabric of regional communities, a long-term risk to regional resilience and value.
Deconstruction of the Source Event
This deconstruction draws on published lender rate cards and product terms, land transaction reporting and regulatory filings from late 2025. The key facts as reported are:
- The ‘Sustainability Risk Premium’: Lenders have established a quantifiable cost-of-capital differential based on ESG data, ranging from a 0.65% discount on CEFC-backed green loans to a 1.15% incentive from NAB for verifiable emissions-reduction activity.
- The ‘Brown Penalty’ rate: Family farms unable to provide the required data are pushed onto standard variable rates, such as NAB’s ‘Farmer’s Choice Variable Rate’ at 8.97%, while compliant corporates can access rates as low as 6.5%—an asset reallocation differential of up to 2.47%.
- The regulatory driver: Mandatory Scope 3 emissions reporting under the ASRS requires Tier 1 banks to calculate the ‘financed emissions’ of their loan books, effectively outsourcing the data compliance burden to borrowers.
- The ‘Brown Discount’ on collateral: Valuers are incorporating a ‘brown discount’ for land that lacks environmental baselining, reducing the valuation of the primary asset of data-poor farms and further restricting their access to capital.
- Accelerated corporate consolidation: 2025 transaction reporting shows a ‘flight to scale’, with corporate aggregators such as PSP Investments and Hewitt acquiring large land portfolios in consolidation hotspots including the Queensland grazing belts and the NSW Wheatbelt, leveraging their access to more competitive green finance.
- Limited government support: Federal ‘transition support’ programs, such as the $17.5 million Carbon Farming Outreach Program, are fiscally immaterial at about 0.017% of the total rural debt pool and insufficient to cover the capital expenditure required for on-farm data infrastructure.
Critical Analysis & Balanced View
The ‘Green Credit Squeeze’ is not a conspiratorial action but the logical, emergent outcome of misaligned incentives. For banks, pricing data-opacity as credit risk is a rational response to their own obligations under the ASRS. They are not targeting family farms; they are de-risking their balance sheets. The asset reallocation is a second-order effect of a top-down regulatory framework that did not adequately account for the disparity in data-readiness across the agricultural sector.
The central paradox is that a policy intended to promote environmental sustainability is materially affecting the social sustainability of rural communities. By favouring capital-intensive, data-rich corporate models, the framework penalises the smaller, often more locally invested family operations that form the bedrock of regional economies, pointing to an agricultural landscape that is ‘greener’ on paper but structurally depopulated.
The unquantified risk for corporate aggregators is reputational and regulatory. As the Wealth Funnel effect becomes more pronounced, the political narrative could shift toward inquiries, levies on foreign ownership or changes to the ASRS framework. The opportunity lies with second-tier lenders, ag-tech firms and advisory services that can build a ‘compliance-as-a-service’ model, offering scalable, low-cost data solutions that help family farms bridge the data gap and access more competitive finance.
Strategic Implications for Property Professionals
- For valuers and rural agents: Valuation method must now include a ‘data-readiness’ assessment. An asset’s ability to generate ISSB-compliant emissions data is a direct driver of its value and liquidity. A checklist scoring assets on data infrastructure (precision-agriculture systems, digital mapping, carbon baselining) supports the application of a Green Premium or Brown Discount.
- For agribusiness finance brokers: The value proposition is no longer just the lowest rate but navigating the data compliance maze. ‘Transition finance’ packages that bundle the cost of data infrastructure into the loan facility demonstrate a clear return to the lender through the unlocked rate discount.
- For institutional investors and fund managers: The arbitrage is clear, but the ESG risk is evolving. Acquiring ‘brown’ assets and converting them to ‘green’ offers uplift; portfolio strategy must now carry a political risk buffer, monitoring government and public sentiment toward corporate farm ownership for regulatory headwinds.
- For buyers’ agents and family office advisers: Due diligence on agricultural acquisitions must extend beyond soil and water to a full digital and compliance audit, prioritising assets with existing data systems or a clear, cost-effective pathway to compliance. For clients looking to exit, a ‘data prospectus’ that pre-emptively baselines the farm’s emissions profile can lift the sale price and widen the buyer pool.
Index Relevance
The APN Codex 24000 Series translates market forces into measurable indices. The indices below are the frameworks this event bears on. None carries a certified reading derived from it; the figures in this piece are source-reported and are not index inputs.
- APN Climate-Risk Asset Devaluation Index™ (24500): the explicit pricing of transition risk into credit terms is the kind of market event this index is designed to measure.
- APN Regional Brown Discount™ (24520): the 0.65% to 1.15% cost-of-capital differential on data-poor agricultural assets, in consolidation zones such as the Queensland grazing belts and the NSW Wheatbelt, is the clearest published quantification to date of the mechanism this index describes.
- APN Bedrock™ (24110): accelerated corporate consolidation is a stability risk for the affected regions’ social cohesion and local economic diversity.
- APN Symbiotic Intelligence Network™ (24310): the ‘compliance-as-a-service’ offerings emerging in the ag-tech market are a candidate leading indicator of market adaptation.
Disclaimer
The analysis and information contained in this deconstruction are for general informational and strategic purposes only and do not constitute financial, investment, legal, or any other form of professional advice. The Australian Property Network (APN) is a strategic intelligence organisation and is not a licensed financial advisor.
This analysis is based on data and information from third-party sources believed to be reliable; however, APN provides no warranty as to its accuracy, currency, or completeness. Images used in this analysis are for illustrative and conceptual purposes only and may not represent real persons, properties, or events.
All frameworks (Codex 24100-24800) are proprietary to APN.
Property values and market conditions can go up or down. Before making any property or investment decisions, you must conduct your own thorough research and seek independent professional advice tailored to your specific circumstances.
Last updated: 5 September 2026.