
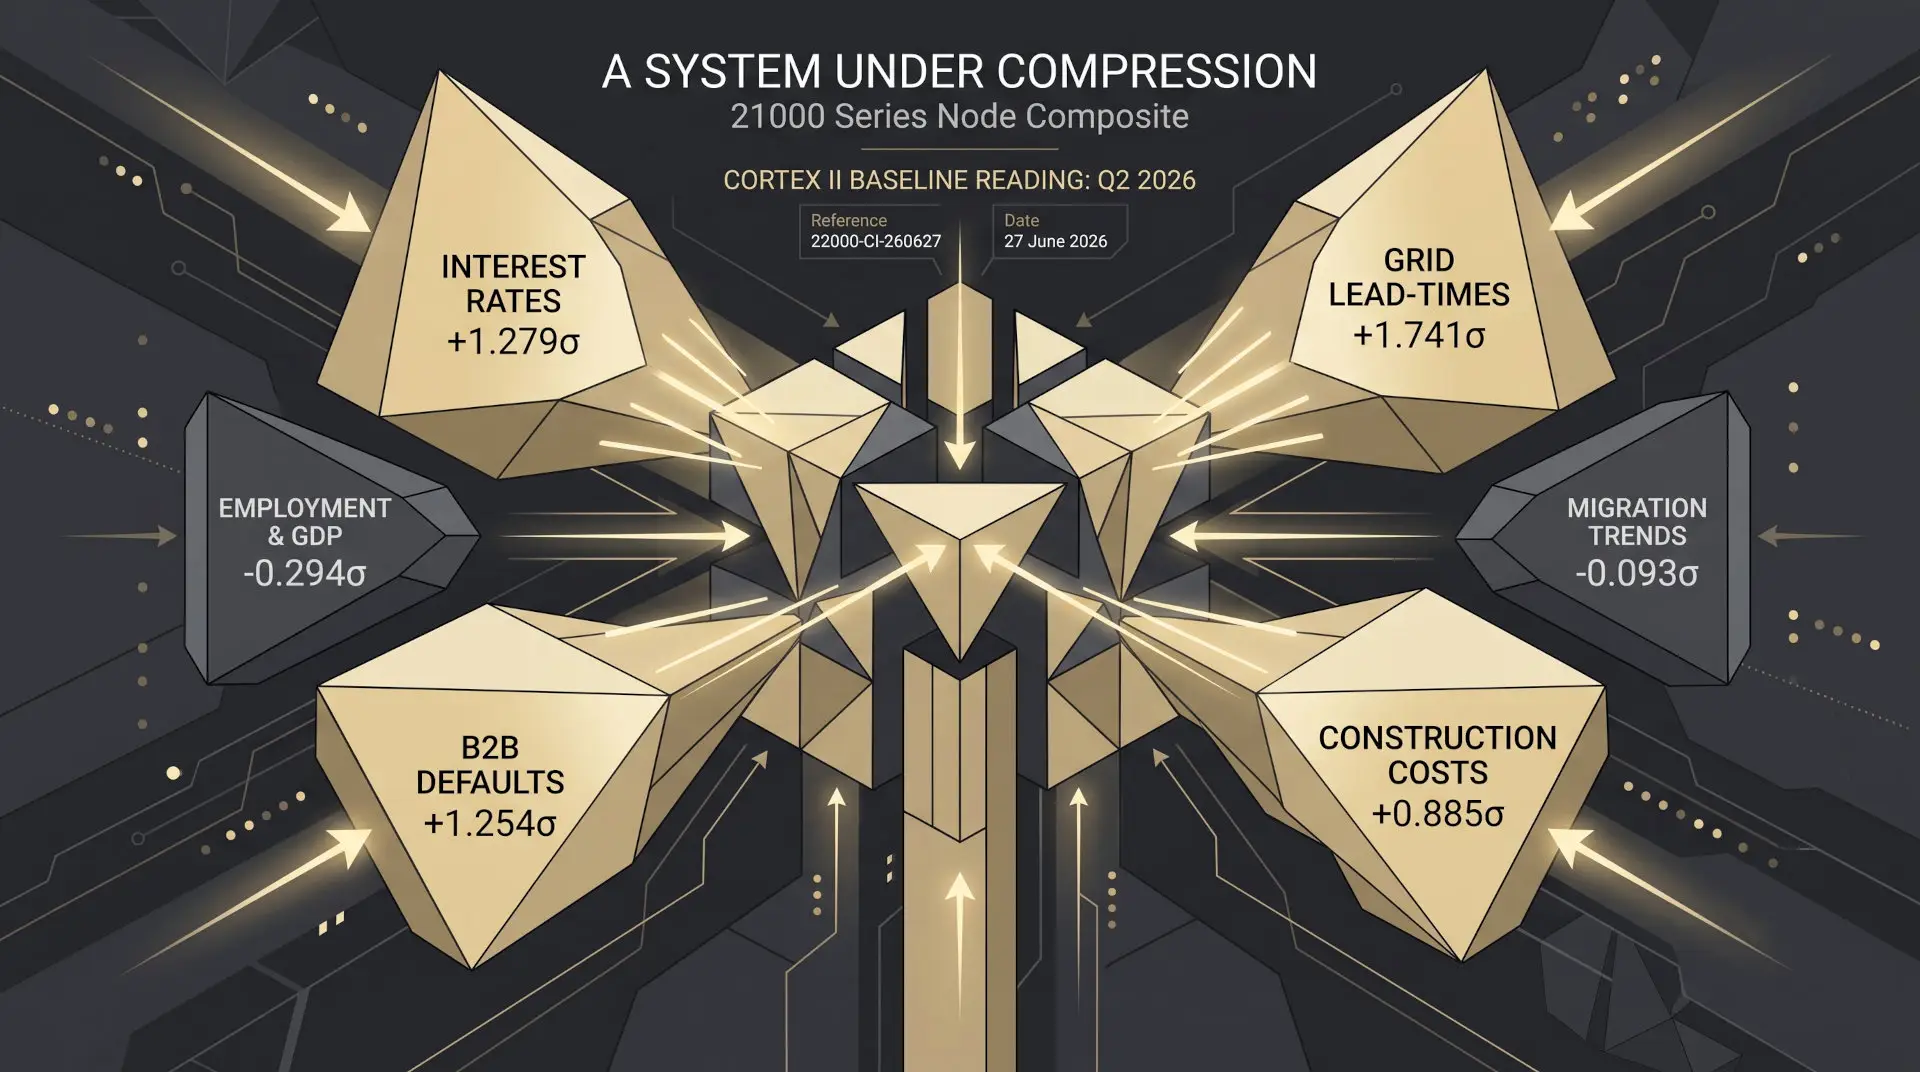

A System Under Compression — 21000 Series Node Composite: Q2 2026
Analytical Preface
This reading presents the current state of the APN Codex 21000 Series node composite — the sovereign data layer of the Codex architecture — as at 31 August 2026. It does not present new primary data. It synthesises the z-score outputs of nine active nodes into a forward-facing assessment of the structural operating environment. The Cortex II inference boundary applies throughout: analytical claims extend only as far as the current node readings support. No declarative forward statements are made.
Node observations carry differing currency. Two nodes (21220, 21230) are current to Q2 2026. Four nodes (21210, 21240, 21260, 21290) carry Q1 2026 readings. Two nodes (21250, 21270) carry Q4 2025 readings. Node 21280 carries an FY2024-25 annual reading, materially more lagged than the rest of the set, and is treated as directional context only.
The current configuration of the APN Codex 21000 Series node composite does not present as a system in retreat. It presents as a system under broad, sustained elevation — in which the cost of capital, the cost of production, infrastructure constraint, and inflation are all reading above their historical baselines simultaneously, while the two nodes most closely tied to household and migration demand sit at or marginally below zero. This is a materially different configuration from one in which cost pressures are offset by a clear demand-side retreat, and it warrants a reading on its own terms.
Two nodes are current to Q2 2026: Inflation (21220), which reads +2.105σ — the second-highest reading in the active composite — and Employment & GDP (21230) at +0.595σ. Four further nodes carry Q1 2026 observations; two carry Q4 2025; one, B2B Invoice Default Velocity, carries an annual FY2024-25 reading and is materially more lagged than the rest of the set.
Infrastructure and Construction Constraints
Grid Connection Lead-Times (21290) is the single highest reading in the active composite at +2.414σ, Q1 2026 — infrastructure connection constraints for new development remain substantially elevated relative to their historical norm, and this is both the most material and among the freshest readings in the set. Construction Costs & Supply Chain (21260) reads +1.371σ, also Q1 2026 (recertified on a repaired insolvency input, a measurement change rather than a change in conditions), positioning the cost of production for new housing well above its historical norm.
Together these two nodes describe a supply side under sustained structural pressure from both the cost and the physical-delivery side of development. Neither reading shows any sign of easing on the current data.
Inflation and the Rate Environment
Inflation (21220) at +2.105σ is the second-most-elevated reading in the composite, and one of the two freshest. Interest Rates (21210) reads +1.005σ at Q1 2026 — elevated, though well below the most material readings recorded elsewhere in the set. Read together, the cost of finance and the cost of living both remain materially above their historical baselines, with inflation the more acute of the two on the current data.
Employment Holds Positive
Employment & GDP (21230) reads +0.595σ at Q2 2026 — modestly positive, with the GDP level and filled-jobs components above their trending baselines and both unemployment measures below. On the current certified data, the labour market shows no clear negative turn; it sits above its historical baseline rather than in measurable softening.
The Household and Migration Counterweight
Household Finance & Consumer Sentiment (21240) reads +0.014σ at Q1 2026 and Migration Trends (21250) reads −0.094σ at Q4 2025 — the two readings closest to zero in the active composite, and the latter the only negative one. Neither constitutes a demand-side contraction signal on the current data; both describe conditions close to their long-run historical norm rather than measurable retreat.
Credit and Business Stress
Real-Time Credit Velocity (21270) reads +0.770σ at Q4 2025, two quarters behind the freshest node in the set. B2B Invoice Default Velocity (21280) reads +1.380σ on an FY2024-25 annual reference — materially more lagged than every other node in the composite, and treated here as directional context only pending a more current, quarter-aligned reading.
Composite Configuration
The 21000 Series node composite as at 31 August 2026 presents the following configuration: eight of nine active nodes read positive, two of them — Inflation and Grid Connection Lead-Times — above +2.0σ; the only negative reading in the set, Migration, is marginally below zero, with Household Finance marginally above it; and the most lagged node in the composite, B2B Invoice Default Velocity, carries an annual rather than quarterly reference and cannot be weighted as a current signal.
This is a broadly elevated environment, not a compression environment defined by an offsetting demand-side retreat. The certified data does not currently show a clear negative counterweight of comparable magnitude to the elevated cost, inflation, and infrastructure-constraint nodes. Whether the near-zero household and migration readings develop into a corrective signal, or the currently-elevated nodes begin to ease, will only be observable as the next quarterly certification cycle lands.
The Cortex II inference boundary at this baseline: the composite is consistent with a market environment in which cost, inflation and infrastructure-constraint pressures remain broadly and simultaneously elevated, with no certified demand-side signal yet of comparable magnitude to offset them. Forward inference beyond this point requires certified node metrics and a formal AUS-Series research protocol.
Findings are presented on the basis of data and evidence alone.
